Not tax or legal advice. This page sorts public sources, as of 1 Nov 2026. Whether and how any of it applies to you is a question for your tax adviser.
In short
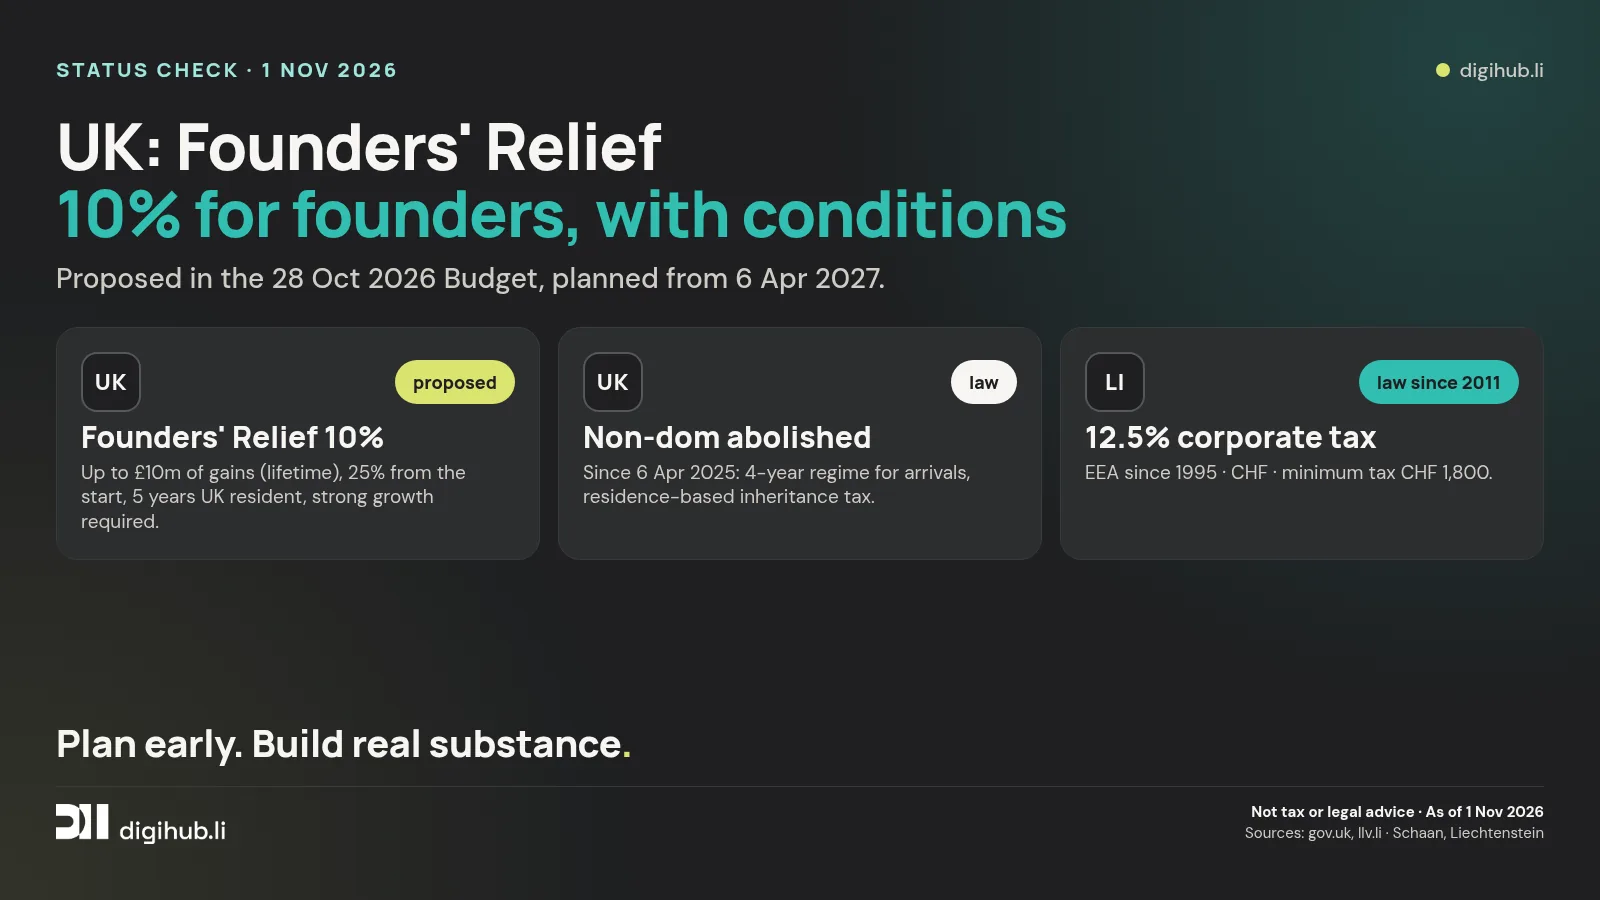
- In the 28 Oct 2026 Budget the government proposed a new Founders' Relief: 10% capital gains tax on up to £10m of gains over a lifetime, for disposals from 6 Apr 2027. Proposed, not law.
- The bar is high: at least 25% of the shares from the start of trading, held for 5 tax years, 5 continuous years of UK residence. The company needs a substantial UK presence, at least £10m turnover, 15 full-time staff and strong growth or R&D.
- The non-dom regime (remittance basis) was abolished on 6 Apr 2025. There is a 4-year regime for arrivals, and inheritance tax now follows long-term residence.
- The UK has no general exit tax for individuals. But if you return within 5 years, gains from your time abroad can be taxed.
- Founders' Relief requires UK residence and a UK company. If you leave, you generally don't use it. That's a location decision, not only a tax question.
Status check 1 Nov 2026
What applies in the UK, and what's proposed?
Sorted, with sources. Founders' Relief would come via amendments to Finance Bill 2026; a technical consultation is running.
UKproposed
Founders' Relief
- 10% capital gains tax on qualifying disposals from 6 Apr 2027, lifetime limit £10m (gov.uk, 28 Oct 2026). Main rates today: 18% and 24%.
- Individual: at least 25% of ordinary share capital from the start of trading, shares held for 5 tax years, UK resident for 5 continuous tax years.
- Company: within UK corporation tax, substantial UK presence over 5 accounting periods, trading, turnover of at least £10m and at least 15 full-time employees, plus 2 of 3 growth or R&D tests.
- Sectors excluded from EIS are excluded here too. The government expects around 600 individuals a year to qualify.
UKlaw
Non-dom abolished
- The remittance basis ended on 6 Apr 2025 (gov.uk).
- New: a 4-year regime for foreign income and gains, for people not UK resident in the previous 10 tax years (gov.uk).
- Residence-based inheritance tax: you're long-term resident if UK resident in 10 of the last 20 tax years. After leaving, it can follow you for up to 10 years (gov.uk).
UKlaw
No exit tax, but a return rule
- The UK doesn't tax individuals' unrealised gains when they leave.
- But: if you were resident in 4 of the 7 years before leaving and return within 5 years, certain gains from your time abroad are taxed in the year you return (HMRC HS278).
As of 1 Nov 2026. Founders' Relief: proposed. Non-dom reform: law in force.
What it honestly means
The UK is taking a different route from France or Italy: a rate for founders, but only for those who stay. Three things matter:
- The relief only comes with UK substance. Founders' Relief requires 5 years of UK residence and a growing UK company. It shows how states think today: benefits follow real presence.
- Substance, not a mailbox. An address alone is neither a residence nor a company seat. If you build something in Liechtenstein, you need a real presence: a registered company with its seat and desks on the ground, a team, and decisions made here. More: Substance in Liechtenstein.
- Plan for a possible return. If you leave the UK and might come back, know the 5-year rule and the inheritance tax tail. Double taxation questions come on top: Double taxation and Liechtenstein.
Why we still like talking about Liechtenstein: the environment is predictable. Founders plan in years, not in headline cycles.
Exit taxes in Europe compared
Almost everywhere, what grew in the old country is taxed. A short comparison as of 1 Nov 2026. Every country including wealth and data taxes: Tax news Europe.
| Country | Status 1 Nov 2026 | Source |
|---|---|---|
| Italy | Government bill, not law. 26% on unrealised gains from €800,000 in financial assets, resident 6 of 10 years, planned from 1 Jan 2027. | Il Sole 24 Ore |
| Germany | Law in force. From a 1% stake in a corporation and 7 of 12 years fully taxable: the gain in the shares is taxed on moving away. Instalments over seven years on application. | § 6 AStG (German) |
| France | Law in force, change at first reading. From €800,000 in securities, resident 6 of 10 years. Today the tax lapses after 2 or 5 years; on 30 Oct 2026 the Assemblée nationale adopted 15 years at first reading. | Amendment I-462 (French) |
| Norway | Law in force. Moves since 20 Mar 2024: unrealised gains above NOK 3m, payable within 12 years. | Skatteetaten |
| Belgium | Law in force since 2026. Exit tax as part of the 10% capital gains tax. Automatic deferral for EU and EEA states among others; not owed without a sale within 2 years. For Liechtenstein, check case by case. | SPF Finances (French) |
| Netherlands | Law in force for box 2. Leaving with a stake of 5% or more triggers a protective assessment (conserverende aanslag). Box 3 is being rebuilt; that is still in parliament. | Belastingdienst (Dutch) |
| Spain | Law in force. From €4m in shares and holdings, or more than 25% of a company worth more than €1m, resident 10 of 15 years. For moves to an EU or EEA state with exchange of information, by election only due on a sale within 10 years. For Liechtenstein, check case by case. | Art. 95 bis LIRPF (Spanish) |
| Austria | Law in force. Moving away counts as a disposal of capital assets, special rate 27.5%. For moves to an EU/EEA state, on application assessed only on an actual sale. For Liechtenstein, check case by case. | § 27(6) EStG (German) |
| Denmark | Law in force. From DKK 100,000 in shares and usually after 7 years of tax liability, gains count as realised on departure. Interest-free deferral; security required outside the EU and the Nordic countries. For Liechtenstein, check case by case. | Skattestyrelsen (Danish) |
| United Kingdom | No general exit tax. If you return within 5 years, gains made while abroad can be taxed (temporary non-residence). | gov.uk HS278 |
| Ireland | No general exit tax. Return rule for domiciled individuals after no more than 5 years away (holdings of 5% or more, or over €500,000). | Revenue s. 29A |
| Switzerland | No general exit tax for individuals. According to the Federal Department of Finance, the Federal Council considers one ruled out under the constitution. | Federal Department of Finance (German) |
The basics: Exit tax.
Liechtenstein in numbers
| Item | Status | Source |
|---|---|---|
| Corporate income tax | 12.5%, since 2011 (Tax Act in force since 1 Jan 2011) | llv.li, gesetze.li SteG |
| Minimum corporate income tax | CHF 1,800 a year | llv.li |
| EEA | Member since 1995 | gesetze.li |
| Currency | Swiss franc (CHF) | – |
| Blockchain Act (TVTG) | in force since 2020 | gesetze.li |
| GmbH (LLC) | from CHF 10,000 share capital | GmbH fact sheet, llv.li |
| EU list of non-cooperative tax jurisdictions | Liechtenstein is not on it (update 9 Oct 2026) | Council of the EU |
It's not a hack. It's boringly predictable, and that's the point. How incorporation works: GmbH formation in Liechtenstein.
digihub · In der Specki 3, Schaan
Substance means a real place to work
If you're looking at Liechtenstein seriously, you need more than an address: an office, people on the ground, decisions made here. At digihub in Schaan you get real desks, not a mailbox: coworking with a Flex Desk from CHF 169, a Full Desk from CHF 299 or a Private Office from CHF 549 a month, plus meeting room and community. A business address is available by agreement (Registered office & business address).
Come by for a coffee, and we'll see together whether Liechtenstein even makes sense for you.
Read next
- Tax news Europe: all countries at a glance
- Italy exit tax: what the draft says
- France exit tax: 15 years at first reading
- Norway exit tax: the 12-year rule
- Belgium: 10% capital gains tax and exit tax
- Netherlands: box 3 in parliament
- Spain: solidarity tax and exit tax
- Switzerland: JUSO initiative rejected, what applies now
- Austria: inheritance tax called for, exit tax applies
- Denmark: no wealth tax, inheritance duty proposed
- Ireland: 31% capital gains tax in Budget 2027
- Exit tax: the basics
- What does substance mean in Liechtenstein?
- GmbH formation in Liechtenstein
Sources
- gov.uk: Capital Gains Tax, introduction of a new Founders' Relief (28 Oct 2026)
- gov.uk: Reforming the taxation of non-UK domiciled individuals
- gov.uk: 4-year foreign income and gains regime
- gov.uk: Inheritance Tax if you're a long-term UK resident
- gov.uk: HS278 Temporary non-residents and Capital Gains Tax
- gov.uk: technical note, non-UK domiciled individuals
- llv.li: corporate income tax (German)
- Council of the EU: EU list of non-cooperative jurisdictions, update 9 Oct 2026
- llv.li: GmbH fact sheet (German)
Not tax or legal advice. Orientation based on public sources, as of 1 Nov 2026. Founders' Relief may still change in consultation. Please check your own case with a tax adviser or lawyer in the UK and Liechtenstein.
Content from digihub.li · reviewed 1 November 2026.