Not tax or legal advice. This page sorts public sources, as of 1 Nov 2026. Whether and how any of it applies to you is a question for your tax adviser.
In short
- Several European countries are moving on exit, wealth and data taxes. Much of it is proposed or debated, not law.
- This overview keeps it clean: what applies, what's in parliament, what's only being demanded. With a date and a source on every row.
- Status-check pages: Italy, France, Norway, UK, Belgium, the Netherlands, Spain, Switzerland, Austria, Denmark and Ireland.
- Liechtenstein is not a way around other countries' rules. It is a predictable location when there is real substance behind it.
Status check 1 Nov 2026
The three biggest moves
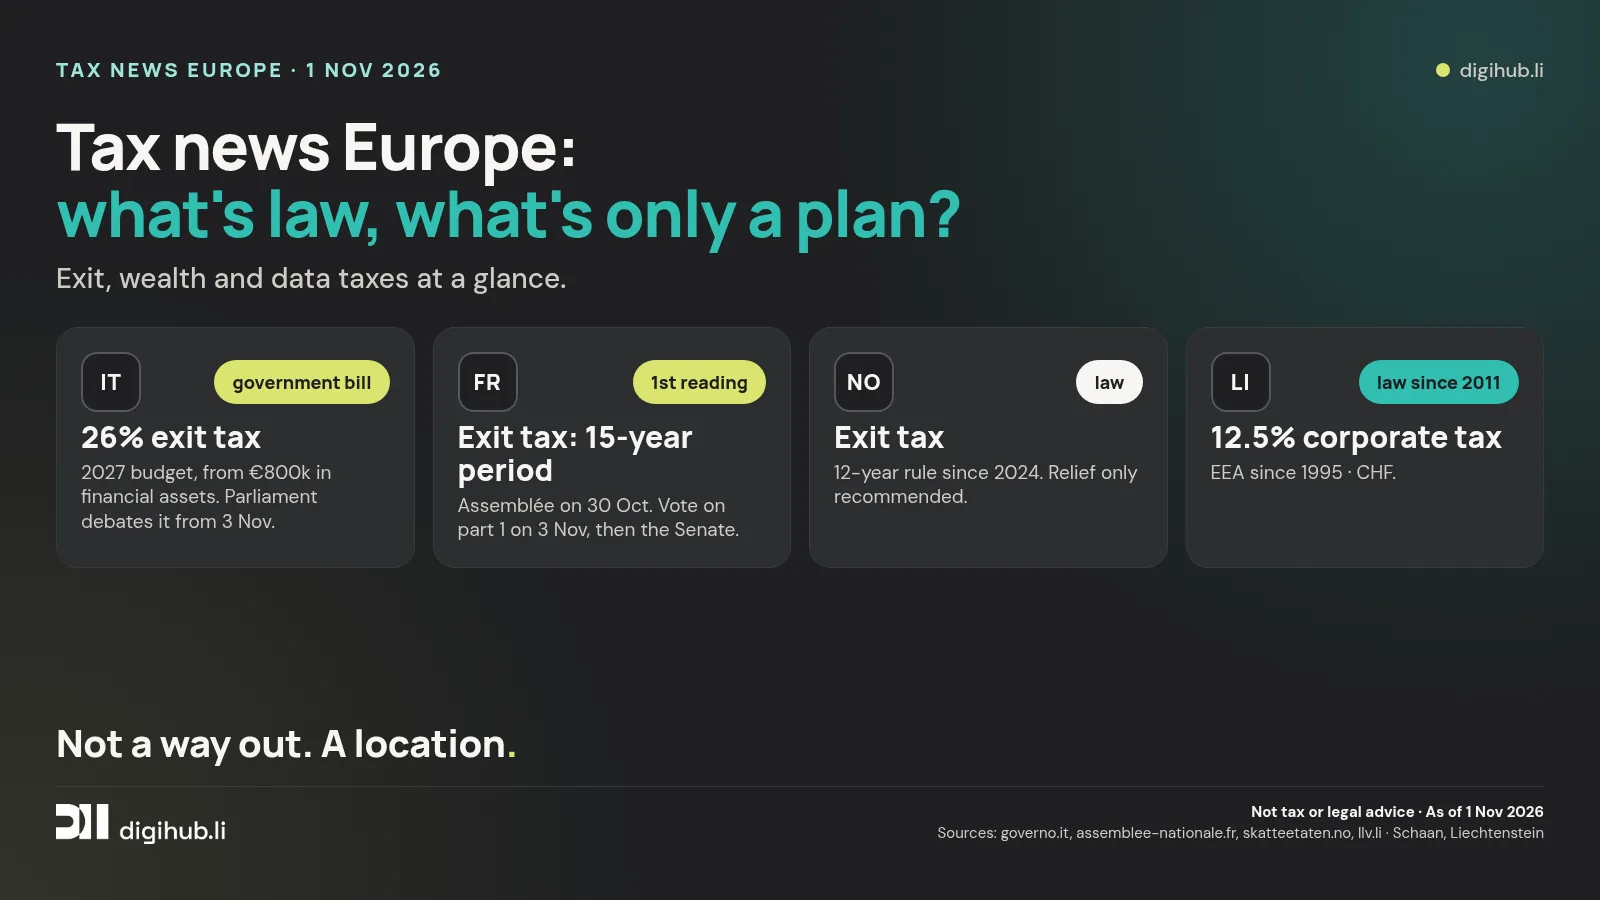
ITgovernment bill
26% exit tax
- Bill approved by the Council of Ministers on 28 Oct, from €800,000 in financial assets.
- Parliament debates it from November; planned from 1 Jan 2027.
- Italy status check
FRfirst reading
Exit tax and data levy
- On 30 Oct the Assemblée nationale adopted a 15-year period for the exit tax and a €0.055 per GB levy.
- Vote on part 1 of the budget on 3 Nov, then the Senate (assemblee-nationale.fr, French).
- France status check
- About the data levy
LIunchanged
Liechtenstein
- 12.5% corporate income tax since 2011, minimum tax CHF 1,800 (llv.li).
- EEA since 1995, Swiss franc.
- Not on the EU list of non-cooperative tax jurisdictions (Council of the EU, 9 Oct 2026).
As of 1 Nov 2026. We update this overview when things change.
Countries at a glance
Status terms: law applies. A government bill has been approved by the government and is in parliament. First reading means one chamber has agreed and further steps are missing. In parliament means the bill is being debated there. Proposed, demanded and in court are open. Rejected is off the table.
| Country | Topic | Status | Date | More |
|---|---|---|---|---|
| IT Italy | Exit tax: 26% on unrealised gains from €800,000 in financial assets (2027 budget bill) (Source: Il Sole 24 Ore) | government bill | 28 Oct 2026 | Italy exit tax |
| FR France | Data levy: €0.055 per gigabyte sent to users in France (amendment I-1358) (Source: Assemblée nationale) | first reading | 30 Oct 2026 | AI tax & data levy |
| FR France | Exit tax: period after which it lapses from 2 to 15 years (amendment I-462) (Source: Assemblée nationale) | first reading | 30 Oct 2026 | France exit tax |
| DE Germany | AI tax on AI-driven value creation (Source: tagesschau.de) | demanded | 29 Oct 2026 | AI tax & data levy |
| DE Germany | Exit tax on holdings of 1% or more (§ 6 AStG) (Source: gesetze-im-internet.de) | law | in force | Exit tax |
| DE Germany | Inheritance tax: business-asset rules before the Federal Constitutional Court, ruling pending (Source: EY) | in court | 12–13 Oct 2026 | coming soon |
| NO Norway | Exit tax with 12-year rule and wealth tax; tax commission recommends relief (Source: Skatteetaten) | law | since 20 Mar 2024 | Norway exit tax |
| BE Belgium | 10% capital gains tax on financial assets, with an exit tax on departure (Source: SPF Finances) | law | since 1 Jan 2026 | Belgium capital gains tax |
| UK United Kingdom | Founders' Relief: 10% on founder gains up to £10m, from 6 Apr 2027, 5 years of UK residence required (Source: gov.uk) | proposed | 28 Oct 2026 | UK tax news |
| UK United Kingdom | Non-dom regime abolished, residence-based inheritance tax (Source: gov.uk) | law | since 6 Apr 2025 | UK tax news |
| NL Netherlands | Box 3: tax on the actual return. Passed the Tweede Kamer, the Eerste Kamer awaits an amending bill, start planned for 2028 (Source: Eerste Kamer) | in parliament | 12 Feb 2026 | Netherlands box 3 |
| ES Spain | Solidarity tax on large fortunes above €3m, extended indefinitely at the end of 2023 (Source: Agencia Tributaria) | law | since 2022 | Spain wealth tax |
| ES Spain | Exit tax from €4m in shares or more than 25% of a company worth more than €1m (Art. 95 bis LIRPF) (Source: BOE) | law | since 2015 | Spain wealth tax |
| CH Switzerland | Popular initiative for a 50% inheritance tax above CHF 50m (Source: EFD) | rejected | 30 Nov 2025 | Switzerland tax news |
| CH Switzerland | Individual taxation approved, in force from 1 Jan 2032; vote on the couples initiative on 29 Nov 2026 (Source: EFD) | law | 8 Mar 2026 | Switzerland tax news |
| AT Austria | Inheritance and gift tax on million-euro estates (opposition motion in the finance committee) (Source: Austrian Parliament) | demanded | 21 Oct 2026 | Austria tax news |
| AT Austria | Exit tax on capital assets, 27.5% (§ 27(6) EStG) (Source: RIS) | law | in force | Austria tax news |
| DK Denmark | Inheritance duty: allowance DKK 566,000, plus 15% above DKK 10m (2027 finance bill) (Source: Ministry of Taxation) | proposed | Oct 2026 | Denmark tax news |
| DK Denmark | Exit tax on shares from DKK 100,000 (fraflytterskat), no wealth tax planned (Source: Skattestyrelsen) | law | in force | Denmark tax news |
| IE Ireland | Capital gains tax 33 → 31%, higher gift and inheritance thresholds (Finance (No. 2) Bill 2026) (Source: gov.ie) | in parliament | 19 Oct 2026 | Ireland tax news |
| LI Liechtenstein | 12.5% corporate income tax, minimum tax CHF 1,800 (Source: llv.li) | law | since 1 Jan 2011 | Liechtenstein in numbers |
What it honestly means
- Exit taxes hit those who move late. What's taxed is usually the growth built up until you leave. If you're considering a move, plan early and get advice in both countries.
- Market levies follow the market. A levy like the French data levy hinges on users in France, wherever the provider is based. Moving doesn't change that.
- Substance, not a mailbox. An address alone isn't a seat. You need an office, people on the ground and decisions made here: Substance in Liechtenstein.
The basics: Exit tax and Double taxation.
Liechtenstein in numbers
| Item | Status | Source |
|---|---|---|
| Corporate income tax | 12.5%, since 2011 (Tax Act in force since 1 Jan 2011) | llv.li, gesetze.li SteG |
| Minimum corporate income tax | CHF 1,800 a year | llv.li |
| EEA | Member since 1995 | gesetze.li |
| Currency | Swiss franc (CHF) | – |
| Blockchain Act (TVTG) | in force since 2020 | gesetze.li |
| GmbH (LLC) | from CHF 10,000 share capital | GmbH fact sheet, llv.li |
| EU list of non-cooperative tax jurisdictions | Liechtenstein is not on it (update 9 Oct 2026) | Council of the EU |
It's not a hack. It's boringly predictable, and that's the point. How incorporation works: GmbH formation in Liechtenstein.
digihub · In der Specki 3, Schaan
Substance means a real place to work
If you're looking at Liechtenstein seriously, you need more than an address: an office, people on the ground, decisions made here. At digihub in Schaan you get real desks, not a mailbox: coworking with a Flex Desk from CHF 169, a Full Desk from CHF 299 or a Private Office from CHF 549 a month, plus meeting room and community. A business address is available by agreement (Registered office & business address).
Come by for a coffee, and we'll see together whether Liechtenstein even makes sense for you.
Read next
- Italy exit tax: what the draft says
- France exit tax: 15 years instead of 2?
- Norway exit tax: the 12-year rule
- UK: Founders' Relief and non-dom
- Belgium: capital gains tax and exit tax
- Dutch box 3: what's in parliament?
- Spain: solidarity tax and exit tax
- Switzerland: JUSO initiative rejected, what applies now
- Austria: inheritance tax called for, exit tax applies
- Denmark: no wealth tax, inheritance duty proposed
- Ireland: 31% capital gains tax in Budget 2027
- AI tax & data levy: what's actually law?
- Moving from Germany to Liechtenstein
- Moving from Austria to Liechtenstein
- Moving from Switzerland to Liechtenstein
- GmbH formation in Liechtenstein
Sources
- Italian government: Council of Ministers no. 195 (28 Oct 2026, Italian)
- Il Sole 24 Ore English: exit tax in the 2027 budget bill (31 Oct 2026)
- Assemblée nationale: amendment I-462 (exit tax), adopted 30 Oct 2026 (French)
- Assemblée nationale: amendment I-1358 (data levy), adopted 30 Oct 2026 (French)
- Assemblée nationale: review of part 1 of the PLF 2027 (French)
- tagesschau.de: Minister Prien calls for an AI tax (29 Oct 2026, German)
- § 6 AStG, gesetze-im-internet.de (German)
- EY: inheritance tax before the Federal Constitutional Court (German)
- Skatteetaten: Exit tax
- regjeringen.no: NOU 2026: 9, tax commission (Norwegian)
- SPF Finances: capital gains tax (French)
- gov.uk: Capital Gains Tax, new Founders' Relief
- gov.uk: Changes to the taxation of non-UK domiciled individuals
- Eerste Kamer: Wet werkelijk rendement box 3 (36.748, Dutch)
- Wetgevingskalender: box 3 amending bill (Dutch)
- Agencia Tributaria: solidarity tax on large fortunes (29 Jun 2026, Spanish)
- BOE: Ley 38/2022 (Spanish)
- Swiss Federal Department of Finance: JUSO initiative vote (30 Nov 2025, German)
- Austrian Parliament: press release no. 998 (21 Oct 2026, German)
- BOE: Ley 35/2006 (IRPF), Art. 95 bis (Spanish)
- Swiss Federal Department of Finance: individual taxation from 1 Jan 2032 (German)
- RIS: § 27 EStG 1988 (German)
- Ministry of Taxation: restructuring inheritance duty (Danish)
- Skattestyrelsen: tax on shares when you leave Denmark (Danish)
- gov.ie: Finance (No. 2) Bill 2026 (19 Oct 2026)
- llv.li: corporate income tax (German)
- Council of the EU: EU list of non-cooperative jurisdictions, update 9 Oct 2026
Not tax or legal advice. Orientation based on public sources, as of 1 Nov 2026. Legislation can change quickly. Please check your own case with a tax adviser or lawyer.
Content from digihub.li · reviewed 1 November 2026.