Not tax or legal advice. This page sorts public sources, as of 1 Nov 2026. Whether and how any of it applies to you is a question for your tax adviser.
In short
- France has had an exit tax for years (Art. 167 bis CGI). It applies to people who were tax resident in France for at least 6 of the last 10 years and hold securities worth €800,000 or more, or at least 50% of a company's profits.
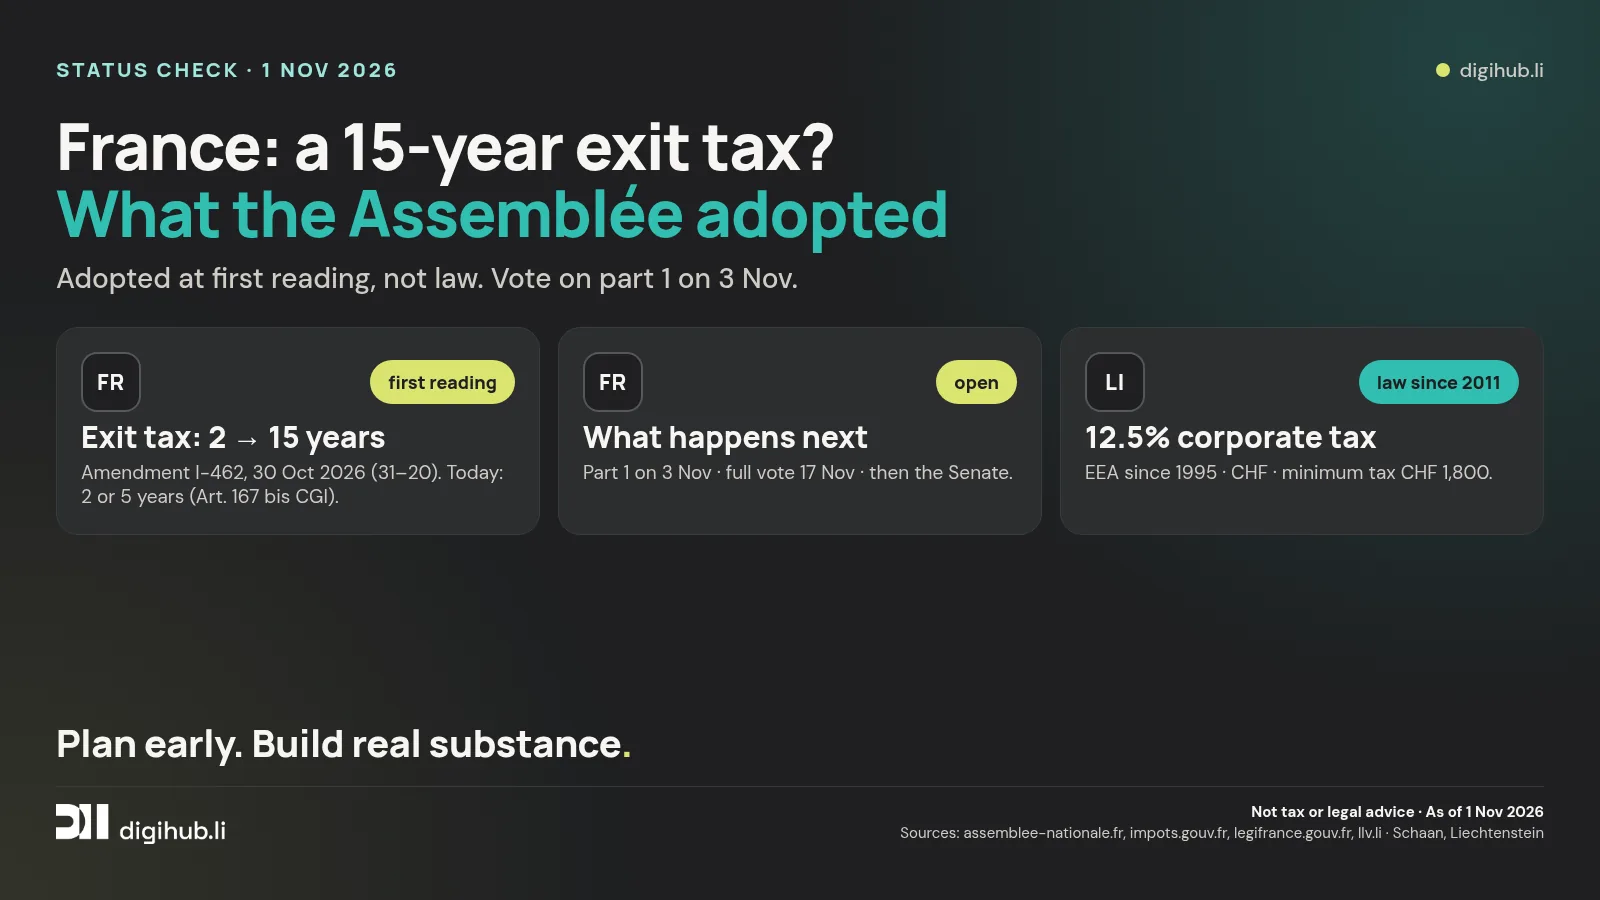
- Today, for moves since 2019, the tax on unrealised gains lapses after 2 years if the shares are still held. For holdings above €2.57m it is 5 years.
- On 30 Oct 2026 the Assemblée nationale adopted amendment I-462 to the 2027 budget at first reading. The period would rise to 15 years. It is not law.
- On 3 Nov 2026 the Assemblée votes on the whole of part 1 of the budget, followed by the Senate and conciliation. In 2024 and 2025 part 1 was rejected in the Assemblée, and the 15-year period fell with it each time.
- Liechtenstein doesn't override French rules. Whether the automatic deferral applies to a move to Liechtenstein has to be checked case by case.
Status check 1 Nov 2026
What applies in France, and what was adopted?
Sorted, with sources. Adopted at first reading means the text can still fall or change later in the process.
FRlaw
What applies today
- Art. 167 bis CGI: unrealised gains on securities are taxed on departure (impots.gouv.fr, French).
- Threshold: securities from €800,000 or at least 50% of a company's profits, plus tax residence for 6 of 10 years.
- Moves since 1 Jan 2019: the tax lapses after 2 years, or 5 years above €2.57m, if the shares are still held. Before 2019 it was 15 years.
- Automatic deferral without security for moves to an EU state or a state with conventions on administrative and recovery assistance that isn't non-cooperative. Otherwise on request (form 2074-ETD) with guarantees, at least 90 days before leaving.
FRfirst reading
Amendment I-462
- Filed on 8 Oct 2026 to the 2027 budget bill, adopted in plenary on 30 Oct 2026 (text, vote no. 9355: 31 for, 20 against, 35 abstentions; French).
- Content: 15 instead of 2 years; the 5-year rule for large holdings goes.
- The text also ties the automatic deferral to states party to the EEA Agreement. What that means in practice depends on the final text.
- The rapporteur and the government opposed it. The minister said he was open to a period in between.
FRopen
What happens next
- 3 Nov 2026: formal vote on part 1 of the budget (assemblee-nationale.fr, French).
- 17 Nov 2026: vote on the whole bill, end of the first reading in the Assemblée. Then the Senate and conciliation.
- The amendment only stays in play if part 1 is adopted. In 2024 and 2025 part 1 was rejected.
As of 1 Nov 2026. Not law. We will update this page after the vote on 3 Nov.
What it honestly means
"15 years adopted" quickly turns into "15 years from now on" online. That is not quite right. Three things matter:
- Exit taxes hit those who move late. What's taxed is the growth built up in France until you leave. If you're seriously considering a move, plan early and get advice in both countries, rather than reacting to a vote.
- Substance, not a mailbox. An address alone is neither a residence nor a company seat. If you build something in Liechtenstein, you need a real presence: a registered company with its seat and desks on the ground, a team, and decisions made here. More: Substance in Liechtenstein.
- Moving doesn't erase your home country's rules. France applies its own rules to decide whether someone has really left and which deferral applies. Double taxation questions come on top: Double taxation and Liechtenstein.
- What else was adopted. The same week the Assemblée adopted, at first reading, a data levy of €0.055 per GB (I-1358) and an extension of the holding tax to cash and financial assets in asset-holding companies (I-3807). That is not law either. More on the data levy: AI tax & data levy.
Why we still like talking about Liechtenstein: the environment is predictable. Founders plan in years, not in headline cycles.
Exit taxes in Europe compared
Almost everywhere, what grew in the old country is taxed. A short comparison as of 1 Nov 2026. Every country including wealth and data taxes: Tax news Europe.
| Country | Status 1 Nov 2026 | Source |
|---|---|---|
| Italy | Government bill, not law. 26% on unrealised gains from €800,000 in financial assets, resident 6 of 10 years, planned from 1 Jan 2027. | Il Sole 24 Ore |
| Germany | Law in force. From a 1% stake in a corporation and 7 of 12 years fully taxable: the gain in the shares is taxed on moving away. Instalments over seven years on application. | § 6 AStG (German) |
| France | Law in force, change at first reading. From €800,000 in securities, resident 6 of 10 years. Today the tax lapses after 2 or 5 years; on 30 Oct 2026 the Assemblée nationale adopted 15 years at first reading. | Amendment I-462 (French) |
| Norway | Law in force. Moves since 20 Mar 2024: unrealised gains above NOK 3m, payable within 12 years. | Skatteetaten |
| Belgium | Law in force since 2026. Exit tax as part of the 10% capital gains tax. Automatic deferral for EU and EEA states among others; not owed without a sale within 2 years. For Liechtenstein, check case by case. | SPF Finances (French) |
| Netherlands | Law in force for box 2. Leaving with a stake of 5% or more triggers a protective assessment (conserverende aanslag). Box 3 is being rebuilt; that is still in parliament. | Belastingdienst (Dutch) |
| Spain | Law in force. From €4m in shares and holdings, or more than 25% of a company worth more than €1m, resident 10 of 15 years. For moves to an EU or EEA state with exchange of information, by election only due on a sale within 10 years. For Liechtenstein, check case by case. | Art. 95 bis LIRPF (Spanish) |
| Austria | Law in force. Moving away counts as a disposal of capital assets, special rate 27.5%. For moves to an EU/EEA state, on application assessed only on an actual sale. For Liechtenstein, check case by case. | § 27(6) EStG (German) |
| Denmark | Law in force. From DKK 100,000 in shares and usually after 7 years of tax liability, gains count as realised on departure. Interest-free deferral; security required outside the EU and the Nordic countries. For Liechtenstein, check case by case. | Skattestyrelsen (Danish) |
| United Kingdom | No general exit tax. If you return within 5 years, gains made while abroad can be taxed (temporary non-residence). | gov.uk HS278 |
| Ireland | No general exit tax. Return rule for domiciled individuals after no more than 5 years away (holdings of 5% or more, or over €500,000). | Revenue s. 29A |
| Switzerland | No general exit tax for individuals. According to the Federal Department of Finance, the Federal Council considers one ruled out under the constitution. | Federal Department of Finance (German) |
The basics: Exit tax.
Liechtenstein in numbers
| Item | Status | Source |
|---|---|---|
| Corporate income tax | 12.5%, since 2011 (Tax Act in force since 1 Jan 2011) | llv.li, gesetze.li SteG |
| Minimum corporate income tax | CHF 1,800 a year | llv.li |
| EEA | Member since 1995 | gesetze.li |
| Currency | Swiss franc (CHF) | – |
| Blockchain Act (TVTG) | in force since 2020 | gesetze.li |
| GmbH (LLC) | from CHF 10,000 share capital | GmbH fact sheet, llv.li |
| EU list of non-cooperative tax jurisdictions | Liechtenstein is not on it (update 9 Oct 2026) | Council of the EU |
It's not a hack. It's boringly predictable, and that's the point. How incorporation works: GmbH formation in Liechtenstein.
digihub · In der Specki 3, Schaan
Substance means a real place to work
If you're looking at Liechtenstein seriously, you need more than an address: an office, people on the ground, decisions made here. At digihub in Schaan you get real desks, not a mailbox: coworking with a Flex Desk from CHF 169, a Full Desk from CHF 299 or a Private Office from CHF 549 a month, plus meeting room and community. A business address is available by agreement (Registered office & business address).
Come by for a coffee, and we'll see together whether Liechtenstein even makes sense for you.
Read next
- Tax news Europe: all countries at a glance
- Italy exit tax: what the draft says
- Norway exit tax: the 12-year rule
- Belgium: 10% capital gains tax and exit tax
- Netherlands: box 3 in parliament
- UK: Founders' Relief and non-dom
- Spain: solidarity tax and exit tax
- Switzerland: JUSO initiative rejected, what applies now
- Austria: inheritance tax called for, exit tax applies
- Denmark: no wealth tax, inheritance duty proposed
- Ireland: 31% capital gains tax in Budget 2027
- Exit tax: the basics
- What does substance mean in Liechtenstein?
- GmbH formation in Liechtenstein
Sources
- Assemblée nationale: amendment I-462, PLF 2027 (adopted 30 Oct 2026, French)
- Assemblée nationale: vote no. 9355 (30 Oct 2026, French)
- Assemblée nationale: review of part 1 of the PLF 2027 (French)
- impots.gouv.fr: leaving France and the exit tax (French)
- Légifrance: Art. 167 bis CGI (French)
- Assemblée nationale: amendment I-1358, data levy (French)
- Assemblée nationale: amendment I-3807, holding tax (French)
- llv.li: corporate income tax (German)
- Council of the EU: EU list of non-cooperative jurisdictions, update 9 Oct 2026
- llv.li: GmbH fact sheet (German)
Not tax or legal advice. Orientation based on public sources, as of 1 Nov 2026. The French budget can still change a lot. Please check your own case with a tax adviser or lawyer in France and Liechtenstein.
Content from digihub.li · reviewed 1 November 2026.